

Goldman expects the Fed-related headwind to reverse over time. Its economists continue to forecast no rate hikes, followed by a delayed easing cycle in 2027. Should that view prove correct, the pressure from real yields and ETF selling would eventually fade while the central-bank bid remains firmly in place.
Takeaways by The Dark Side of the Boom™
• Goldman Sachs estimates central banks purchased 81 tonnes of gold in May, with the three-month seasonally adjusted pace running at 67 tonnes per month versus a pre-2022 average of 17 tonnes.
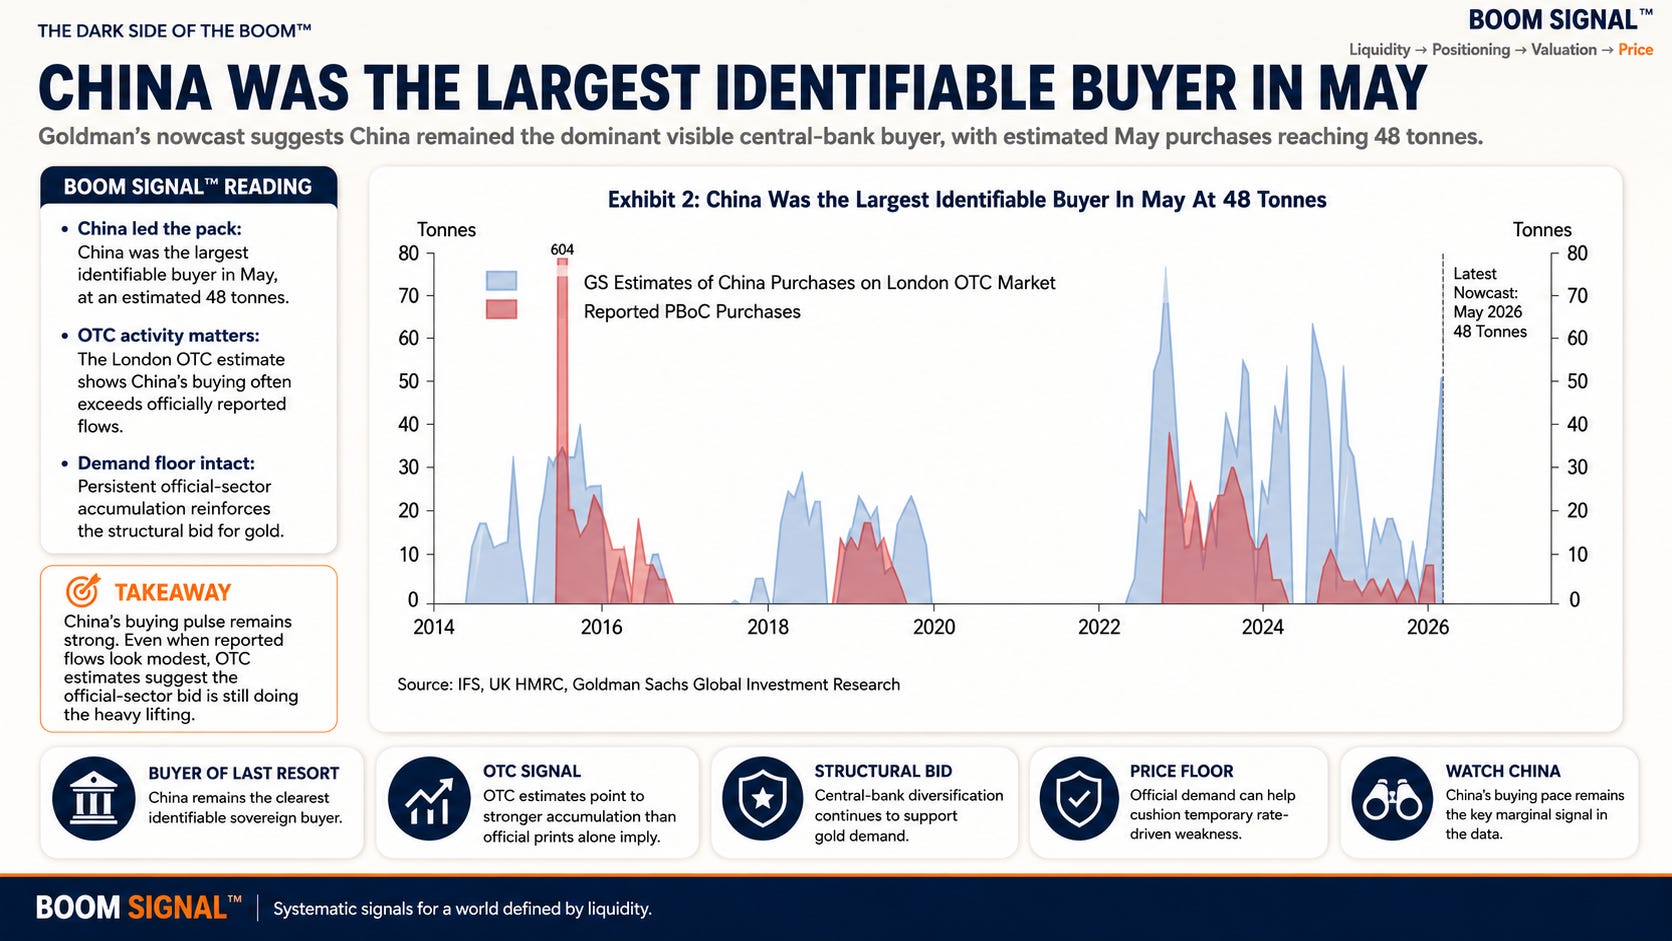
• China was the largest identifiable buyer at an estimated 48 tonnes, helping drive the renewed acceleration in official-sector demand.
• Central-bank diversification remains the foundation beneath Goldman’s $4,900/oz end-2026 forecast.
• Near-term pressure still comes from hawkish Fed pricing, higher real yields and the risk of ETF liquidation.
• For bullion traders, the critical signal will be whether official-sector demand continues absorbing Fed-driven selling before corrections become disorderly.
• The larger upside risk is that private investors begin following central banks into gold as geopolitical fragmentation and fiscal unease deepen.
Central Bank Bid Is Putting a Floor Under Gold
Gold is being asked to walk into a stiff headwind from the Federal Reserve, yet it keeps finding something solid beneath its feet.
Markets are again pricing the possibility of rate hikes as energy-driven inflation creeps back into the policy debate, real yields remain restrictive and ETF investors rediscover the opportunity cost of holding bullion. Normally, that combination would be enough to knock gold off balance. This time, however, the selling is landing on top of a central-bank bid that looks less like opportunistic dip buying and more like a long-term transfer of metal from impatient hands into official vaults.
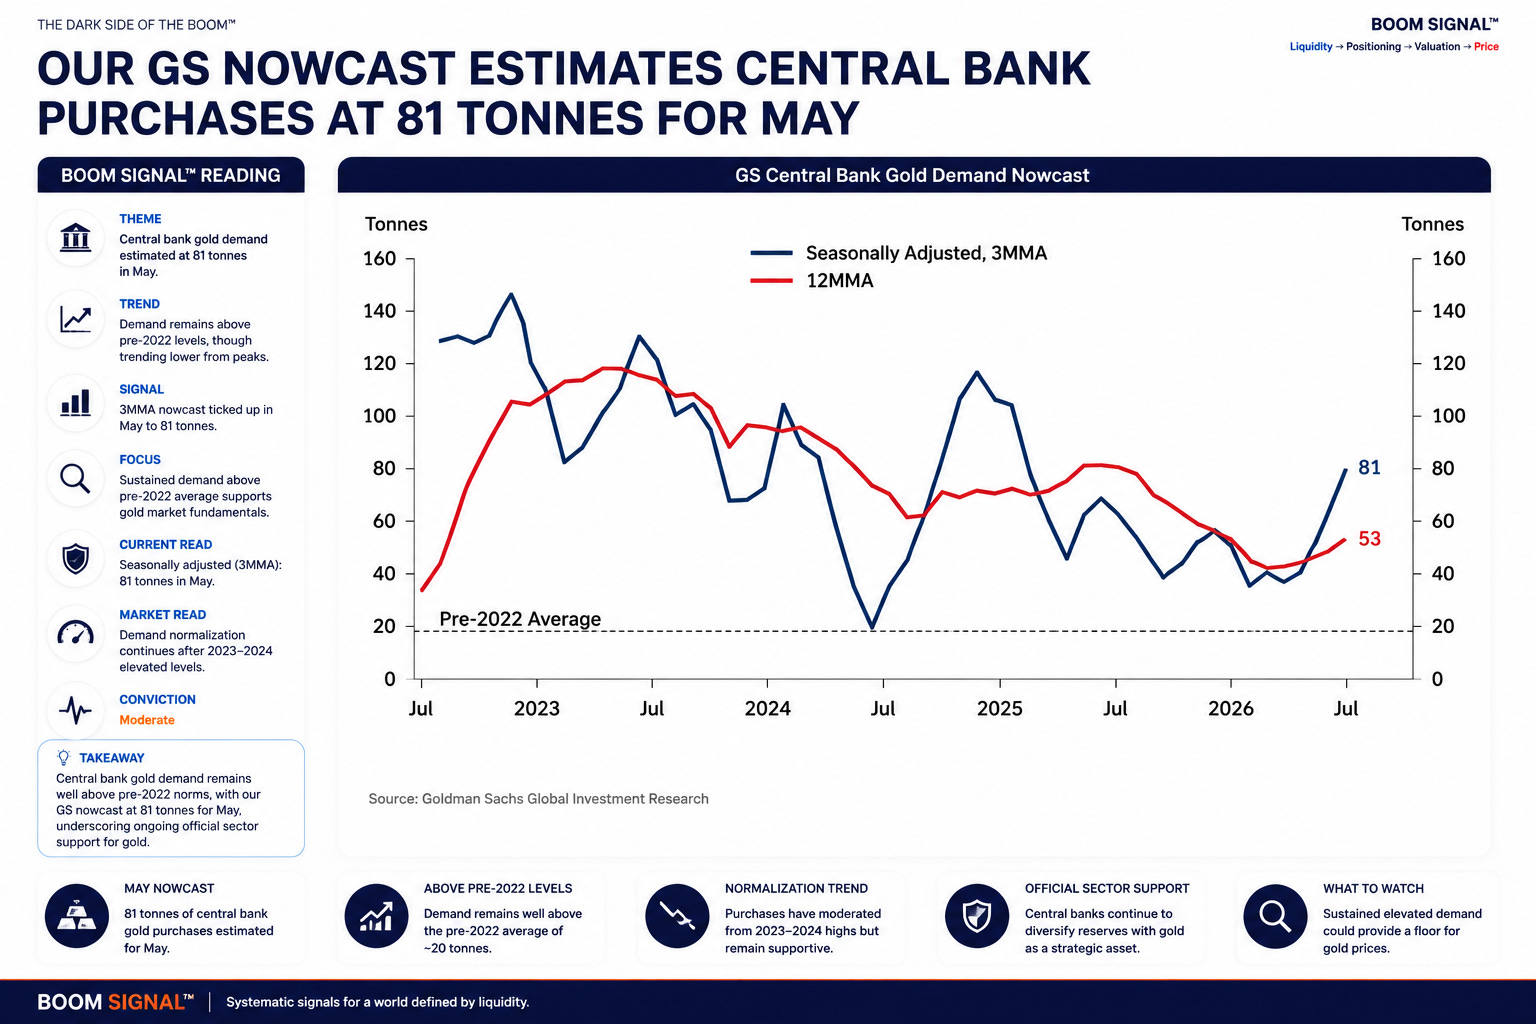
According to Goldman Sachs Global Investment Research and its commodities team, central banks purchased an estimated 81 tonnes of gold in May. On a three-month seasonally adjusted basis, buying was running at 67 tonnes per month, nearly four times the pre-2022 average of 17 tonnes. China was the largest identifiable buyer at an estimated 48 tonnes, helping drive a sharp reacceleration in official-sector demand just as Western investors were becoming more nervous about the Fed.
The numbers matter because central banks do not trade gold the way macro funds or ETF investors do. They are not trying to front-run the next inflation print, fade a Fed speech or squeeze a few basis points out of a real-yield move. They are buying because the political foundations beneath the reserve system no longer look quite as permanent as they once did.
The freezing of Russia’s reserves in 2022 was the moment the lights came on. Emerging-market reserve managers were reminded that foreign assets can carry political conditions as well as financial returns, and that diversification is not merely about spreading risk across currencies. It is also about ensuring that part of the national balance sheet remains beyond the reach of another government’s sanctions machinery.
Gold fits that requirement rather neatly. It does not depend on a foreign issuer, carries no counterparty promise, and, once held domestically, sits outside much of the geopolitical blast radius.
Goldman sees this as a multi-year shift rather than a temporary scramble for protection. The 2026 OMFIF survey cited in the research shows that diversification remains the most common reason reserve managers give for purchasing gold, while protection against geopolitical risk was selected by 51% of respondents, an increase of 11 percentage points from 2024. Meanwhile, 79% believe the global monetary system is moving toward a more multipolar structure.
That is central-bank language for a world in which the old reserve order is beginning to fracture around the edges.
The team maintains its assumption that central banks will buy an average of 50 tonnes per month in 2026 and 40 tonnes per month in 2027. Buying is expected to slow through the summer, as it often does, before picking up again from September. The pace may breathe in and out, but the broader direction remains difficult to mistake.
This persistent official-sector demand is the anchor beneath Goldman’s $4,900/oz end-2026 forecast. It is also why the next gold correction may not behave like the old ones. In previous cycles, higher real yields and a stronger dollar could leave bullion searching for a buyer. Now there appears to be a large, patient and relatively price-insensitive customer waiting below.
That does not mean the Fed has lost its ability to bruise the market.
In the near term, gold still faces a difficult rates backdrop. Markets are pricing the possibility of a Fed hike this year as energy inflation threatens to seep into the broader economy, and that repricing can hit bullion from both sides. Higher yields increase the cost of holding an asset that pays no income, while a more hawkish Fed can temporarily weaken the argument that investors need gold as protection against monetary debasement.
ETF demand is where the pressure is most likely to appear. Central banks may think in decades, but Western portfolio flows can reverse before lunch. When real yields rise and the dollar firms, ETF investors often head for the exits first, leaving futures positioning and leveraged longs to follow behind.
For bullion traders, the important question is not whether the Fed can push gold lower. It can. The question is what the market looks like when that pressure arrives.
If hawkish pricing sparks ETF liquidation but the decline repeatedly runs into strong physical and official-sector demand, then the central-bank bid is no longer simply part of the long-term story. It is actively changing the trading character of the market by absorbing supply that might once have produced a much deeper washout.
That is the tension sitting at the heart of the Goldman view. The short-term market is still controlled by rates, positioning and the dollar, but the longer-term market is being rebuilt by reserve managers who are far less interested in the next Fed meeting than in the direction of the global monetary system.
Goldman expects the Fed-related headwind to reverse over time. Its economists continue to forecast no rate hikes, followed by a delayed easing cycle in 2027. Should that view prove correct, the pressure from real yields and ETF selling would eventually fade while the central-bank bid remains firmly in place.
That would leave gold in a much more favourable position. The market would no longer be trying to climb against the rates wind with only structural support beneath it. The macro backdrop and the official-sector flow would begin pulling in the same direction.
The larger upside risk is that private investors eventually start following central banks into the trade.
Gold remains lightly held in many portfolios, even as geopolitical risk, fiscal strain and doubts over the durability of the Western monetary framework continue to build. Iran and the broader deterioration in the geopolitical backdrop may accelerate that process, particularly if investors begin to view gold not simply as a crisis hedge, but as protection against a reserve system carrying too much debt, too much political baggage and too little room for error.
Gold does not need the entire system to break. It only needs confidence in that system to fray around the edges.
Central banks appear to have already reached that conclusion. They are not waiting for the roof to cave in before buying insurance, and their demand is beginning to place a firmer floor beneath the market.
The Fed may still shake gold hard enough to send weak hands running for the door, and higher real yields can still turn an orderly pullback into something more violent. But each correction now arrives with a buyer underneath that is thinking less about this year’s policy cycle and more about the next decade of monetary fragmentation.
The Fed controls the weather. Central banks are positioning for the climate.