

Hartnett’s endgame for the rates story is unusually specific. A hawkish Warsh at Jackson Hole on August 28, followed by the September 16 FOMC and potentially a Bank of Japan hike on September 18, could collectively deliver what he calls a kind of “Mission Accomplished” moment for yields — enough policy credibility to cap the long end while simultaneously taking the air out of the yen-collapse trade.
Takeaways by Dark Side of the Boom™
The fiscal problem is becoming a rates problem. With debt service near $1.4 trillion and long yields still elevated, Hartnett’s Anything But Bonds framework remains intact — but the quiet outperformance of REITs, biotech, regional banks and small caps suggests markets are starting to sniff out a peak in yields.
Asia is moving from avoidance to selective re-entry. Japan, Korea and Taiwan tech are leading what Hartnett sees as a new secular bull market, while Hong Kong property offers the early contrarian expression before a broader China rotation that still needs a meaningful revival in consumer growth.
Gold remains the cleanest hedge against the policy regime. Hartnett’s Anything But the US Dollar trade is less about one Fed meeting than protection against fiscal dominance, currency debasement, populist spending and a weaker dollar — with the same backdrop increasingly supportive of EM assets.
The AI boom is still alive, but the financing is where the cracks may appear first. Hartnett stays strategically long the bubble while shorting AI bonds as capex explodes and cash flow deteriorates; the bigger risk is political, with affordability, grid pressure and voter backlash increasingly capable of setting the ceiling on the next leg higher.
Gold Is Still the Answer
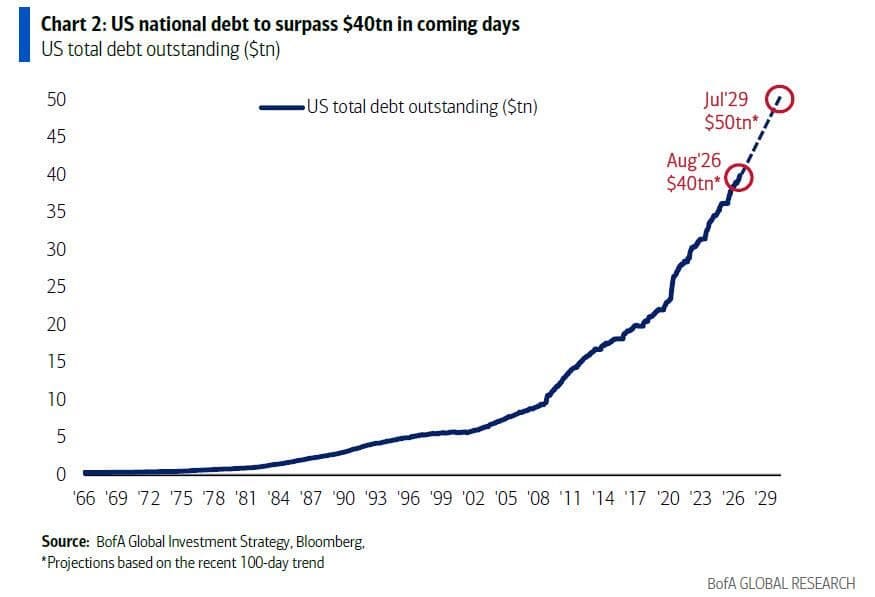
The problem with $40 trillion is not the number. Markets have been watching the US debt clock spin higher for years and, for most of that time, the response has been little more than a shrug. Washington spends, Treasury issues, investors absorb it, and the machine keeps moving.
But round numbers have a habit of concentrating attention, and this one arrives at an awkward moment. The US is now within touching distance of $40 trillion in national debt, just as investors are becoming far less relaxed about the price of financing it. Long-end yields are elevated, the term premium has returned to the conversation, Treasury supply is no longer background noise, and every fresh fiscal promise increasingly comes with a question the market used to avoid asking: who is going to fund it, and at what yield?
That is the backdrop to Michael Hartnett’s latest BofA Flow Show, aptly titled “Strife Begins at Forty.” Hartnett’s warning is not simply that the debt stock is about to cross another historic milestone. His bigger point is the trajectory. Forty trillion is arriving now; on the current path, $50 trillion is already coming into view by 2029.
For traders, though, the debt clock itself is almost the least interesting part of the story. The real question is where that fiscal pressure begins showing up in the market — in bond yields, the dollar, gold, equity leadership, foreign demand for US assets and the increasingly uncomfortable relationship between fiscal expansion and monetary policy.
And that is where Hartnett’s charts become much more interesting than the headline number.
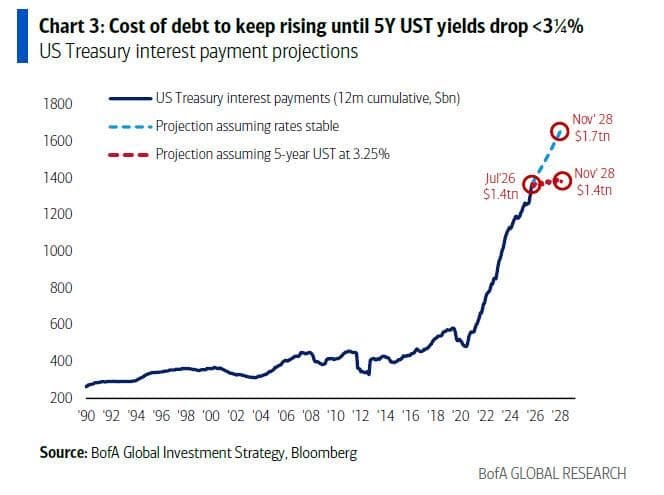
Hartnett’s more important chart, though, is not the debt stock. It is the cost of carrying it.
This is the part of the fiscal story we have been banging on about for years: once the Treasury has refinanced enough of the old cheap debt at today’s rates, the interest bill stops being a footnote and starts eating the budget alive. US debt-service costs have now climbed to roughly $1.4 trillion over the past 12 months, putting interest expense on a trajectory toward becoming one of Washington’s largest single outlays.
And unlike a discretionary spending program, this bill does not respond to political promises. It responds to the level of rates and the speed at which the Treasury has to roll its liabilities.
Hartnett’s threshold is the one traders should circle: 5-year Treasury yields need to fall below roughly 3.25% before the pressure meaningfully eases. That is a very long way from being a painless macro outcome. Getting there probably requires either a sharp collapse in inflation expectations, a material growth shock, or the sort of recessionary repricing that would create an entirely different set of problems for risk assets.
That is the fiscal trap in one chart. Higher yields make the debt arithmetic worse, but the economic conditions required to pull yields low enough to repair the arithmetic are hardly bullish either. The US does not necessarily need a funding crisis for this to matter. It simply needs interest expense to keep compounding faster than nominal growth and tax receipts, forcing an ever-larger share of the budget toward servicing yesterday’s borrowing rather than financing tomorrow’s economy.
For markets, that keeps the long end of the Treasury curve firmly in the fiscal conversation. The bond vigilantes do not need to storm the gates. They only need to keep demanding a little more term premium.
The market’s answer to this fiscal mess has been remarkably simple: own almost anything except duration.
That is the essence of Hartnett’s Anything But Bonds allocation call, and the irony is getting harder to miss. US equities are pushing to fresh highs at the same time the Treasury is being forced to sell 30-year paper at yields north of 5%, levels that would once have been associated with a very different market regime. Hartnett’s dry conclusion — “tracks,” as the kids say — captures the absurdity rather well.
Normally, a 30-year Treasury yield above 5% would be expected to put a fairly obvious ceiling on equity multiples. Instead, the market has split into two worlds. The long end is pricing fiscal excess, supply and a rising term premium, while equities are still pricing productivity, earnings and an AI-driven investment boom powerful enough to outrun the cost of capital.
The problem is that those two worlds are not entirely independent.
The AI capex cycle is increasingly being financed through the same capital markets that Washington depends on to absorb an enormous Treasury issuance calendar. That does not mean corporate borrowing is suddenly going to displace Treasury demand one-for-one, but it does mean there is more competition for balance-sheet capacity and investor capital just as sovereign funding needs are exploding.
That is where the story gets uncomfortable. The same AI boom helping to propel equities higher may also be reinforcing the pressure keeping long-term yields elevated. In other words, the growth narrative supporting stocks is simultaneously making the relative case for long-duration government bonds even harder.
For now, that contradiction has produced a very clean market message: investors will tolerate the fiscal deterioration so long as nominal growth, earnings and liquidity continue to compensate them elsewhere. Hence Anything But Bonds.
The risk comes when one side of that bargain breaks. If growth rolls over, equities lose their earnings shield. If growth stays firm, long yields may remain stubbornly high. Either way, the 30-year Treasury is increasingly where the fiscal argument gets marked to market.
From there, Hartnett widens the lens from the debt problem to the asset-allocation rules of the road for the 2020s. And despite everything markets have thrown at investors over the past few years — inflation, war, AI, fiscal excess and radically higher interest rates — the broad playbook has changed remarkably little.
The decade is still being defined by a shift away from the low-inflation, zero-rate architecture of the 2010s toward a world of bigger government, larger deficits, more volatile inflation and a structurally higher cost of capital. That means the winners and losers are increasingly determined not by whether growth is simply “good” or “bad,” but by which assets can live with that new regime.
Hartnett’s rules remain broadly intact:
ABB (Anything but Bonds),
ABC (Anywhere but China),
ABD (Anything but the US Dollar),
AI (all-in on AI),
Hartnett’s conviction behind this framework has only strengthened in 2026 because, in his view, policymakers have effectively decided that a nominal-GDP boom is the least painful way out of the debt problem, while the stock market has become too economically and politically important to be allowed to fail cleanly. That combination explains why Wall Street continues to trade with remarkably little fear.
And the backdrop certainly gives the bulls plenty to work with. Hartnett points to surging earnings, an estimated $10 trillion increase in household wealth in 2026, and more than $1 trillion of AI capex potentially arriving in 2027. In that environment, the door remains wide open for risk assets to keep running. The constraints are equally clear: a renewed surge in bond yields, a political backlash from voters, and the uncomfortable fact that almost everyone is already leaning toward the upside.
Which brings us back to the first of Hartnett’s four big allocation acronyms: ABB — Anything But Bonds.
The preferred expressions are REITs, biotech/XBI, regional banks/KRE and small caps — precisely the corners of the market that should struggle most if yields are still heading materially higher. That is what makes their recent resilience interesting. Despite higher yields in 2026, these unloved, duration-sensitive assets have begun quietly outperforming, which Hartnett reads as the market starting to discount peak yields over the coming quarters.
There is a historical warning embedded here. Booms and bubbles rarely end because valuations suddenly become offensive; they tend to end when the bond market finally tightens the financial screw hard enough. Hartnett notes that Treasury yields rose roughly 200bp before the Nifty Fifty broke, Japanese government bond yields climbed about 230bp into the end of Japan’s great bubble, and US Treasury yields surged roughly 260bp into 1999. Eventually the cost of money catches up with the story.
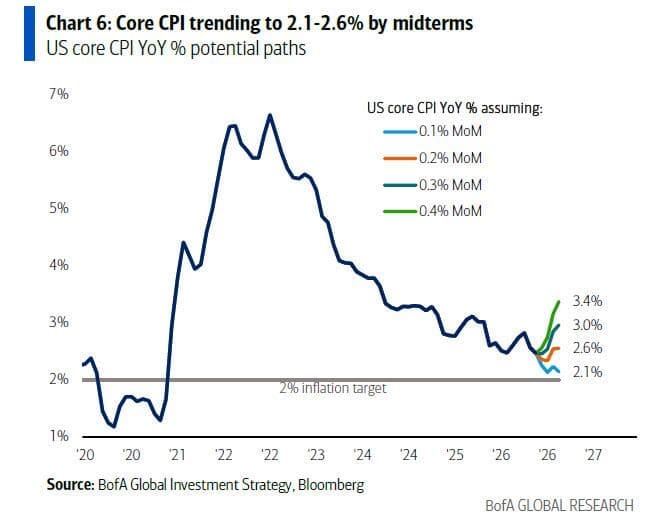
But Hartnett’s more provocative point is that policymakers may now understand that another major leg higher in yields is simply too dangerous to tolerate. The recent US-Japan FX intervention fits that interpretation: Washington has little appetite for a world in which long Treasury yields live sustainably above 5%. If inflation continues drifting lower into the midterms, the authorities gain more room to lean against that outcome.
That is why ABB is becoming more nuanced than simply “avoid bonds.” The interesting signal is that the market’s former duration casualties — REITs, biotech, regional banks and small caps — are beginning to behave as though the bond-yield shock is closer to its end than its beginning.
If that reading is right, the next phase of the risk rally may not belong exclusively to the mega-cap winners that carried the first leg. It may increasingly rotate into the very assets that spent the past several years being crushed by the rise in the discount rate.
Hartnett’s endgame for the rates story is unusually specific. A hawkish Warsh at Jackson Hole on August 28, followed by the September 16 FOMC and potentially a Bank of Japan hike on September 18, could collectively deliver what he calls a kind of “Mission Accomplished” moment for yields — enough policy credibility to cap the long end while simultaneously taking the air out of the yen-collapse trade.
That would matter enormously for the ABB basket. If investors become convinced that the authorities have drawn an informal line under the bond rout, the assets most punished by the rise in yields suddenly have room to breathe. Hence Hartnett’s interest in REITs, biotech, regional banks and small caps: not because the macro backdrop has magically become benign, but because these are precisely the trades with the most torque if the market decides the great duration reset has finally run its course.
From there Hartnett moves to the second rule of the decade: ABC — Anywhere but China.
Except, characteristically, his preferred trade is now hiding right inside the place investors have spent years avoiding.
Hartnett’s secular rule is “buy humiliation, sell hubris,” and it is difficult to find anything in global markets that has endured more humiliation this decade than Chinese assets and real estate. His contrarian expression is therefore long Hong Kong property stocks.
The valuation scar tissue is extraordinary. The Hong Kong property sector is effectively trading around levels last seen three decades ago, after years in which higher rates, China’s property implosion, weak confidence and relentless capital outflows turned what was once one of Asia’s premier wealth trades into something investors barely want to discuss.
And that is exactly the attraction.
This is not a call that China has suddenly fixed its structural problems. Hartnett is looking at the asymmetry created when an asset moves from disliked to institutionally abandoned. At that point, you do not need a return to the glory days to make money. You need the news to become merely less bad, the policy impulse to become marginally more supportive, or the discount rate to stop rising.
That last point connects ABC directly back to ABB. Hong Kong property is one of the purest long-duration casualties in Asia. If global yields are approaching a ceiling at the same time Beijing remains under pressure to stabilize domestic demand and property, then an asset priced for almost perpetual disappointment suddenly acquires considerable convexity.
This is vintage Hartnett: do not chase the market displaying the most confidence; look for the one where confidence has already been beaten out of everybody.
Buy humiliation, sell hubris. After a decade like this one, Hong Kong property certainly clears the first hurdle.
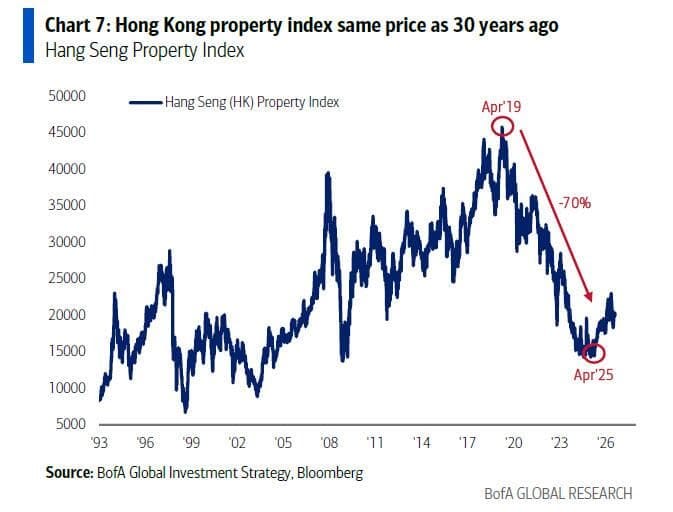
The more interesting extension of Hartnett’s ABC framework is that the regional capital cycle itself may be turning.
He argues Asia is beginning its third secular bull market of the past 40 years, with Japan, Korea and Taiwan technology providing the initial leadership. That is an important distinction. This is not a rerun of the old China-centric Asia trade; the leadership is broader, more technology-heavy and increasingly tied to the global AI and semiconductor cycle.
If that secular allocation shift gathers pace, capital does not remain neatly confined to the first winners. Regional benchmarks attract inflows, mandates broaden and investors begin working their way down the valuation ladder. That is where Hong Kong property becomes interesting at roughly 12x earnings and with sector prices still sitting near levels seen decades ago.
For traders, the setup is less about calling a Chinese macro renaissance than recognizing how regional bull markets eventually create their own breadth. Japan, Korea and Taiwan may open the door, but once global money starts rebuilding Asia exposure, the laggards become much harder to ignore.
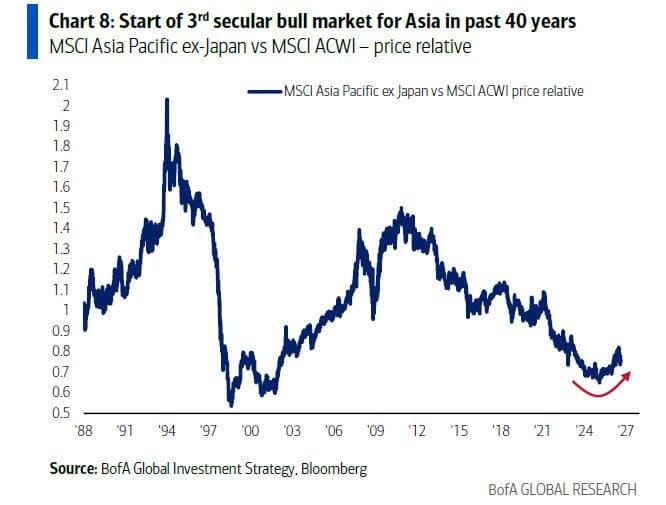
There is another leg to Hartnett’s Asia argument that makes the eventual China rotation more interesting. China is already dominant in EVs and renewables, and its AI ecosystem is becoming another increasingly credible source of market leadership. At the same time, Hong Kong may be regaining some relative appeal as a regional capital hub, with Dubai facing greater geopolitical uncertainty and Singapore becoming less compelling at the margin as taxation rises.
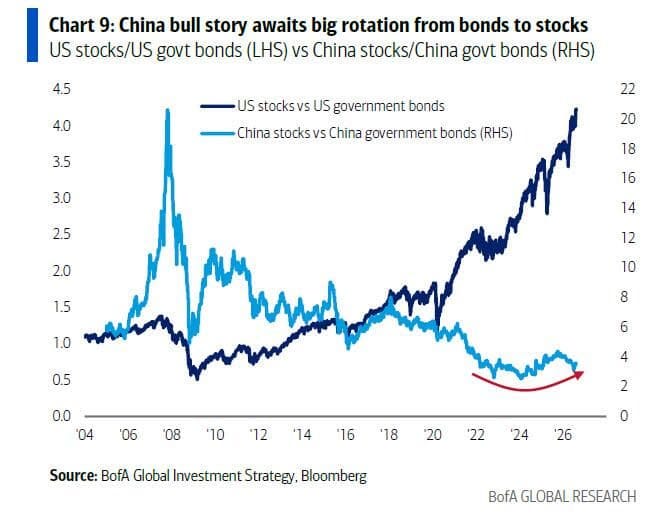
Hartnett is not yet declaring the full Anywhere But China era over. For that, he wants to see something much more fundamental: a genuine acceleration in Chinese consumer growth. That would be the signal capable of pulling domestic capital out of the relative safety of bonds and back into equities, while giving global allocators a reason to rebuild China exposure on something stronger than valuation alone.
Until then, Hong Kong property is the early trade rather than the final one. It offers exposure to the possibility that the regional tide is beginning to turn before the macro confirmation arrives.
That distinction matters. The bigger China equity rotation probably needs consumers to re-engage. Hong Kong property only needs investors to start believing that the worst of the capital, rate and confidence cycle is behind it.
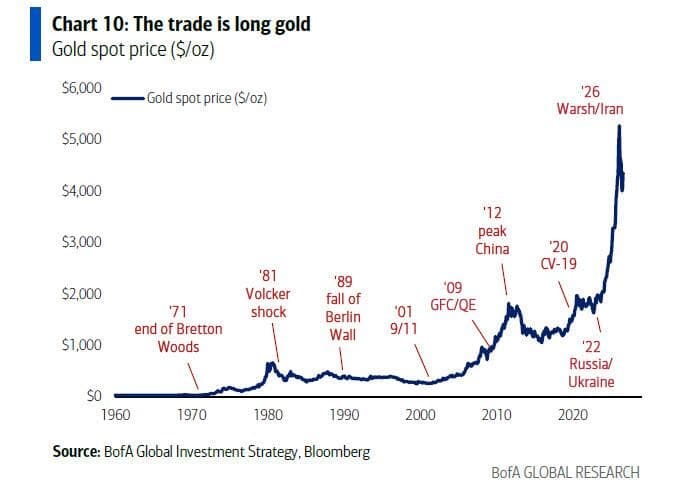
Hartnett’s third rule is ABD — Anything But the US Dollar — and here the expression is straightforward: long gold.
The attraction is no longer just the conventional inflation hedge. Gold has become the cleaner insurance policy against a much wider 2020s regime: currency debasement, a disorderly bond-market repricing, persistent asset inflation and a political system increasingly willing to spend regardless of which flavour of populism is in power.
That last point matters. Hartnett frames the decade as a contest between capitalist populism and socialist populism, but from a market perspective the distinction can become surprisingly narrow. Both roads can lead toward larger fiscal commitments, pressure for easier financial conditions and less willingness to impose the sort of austerity required to stabilise public finances quickly.
Gold does not need to decide which political camp wins. It simply benefits from the growing probability that the eventual policy response involves more nominal growth, more money and a weaker commitment to preserving the purchasing power of cash.
That is why Hartnett still regards it as the best hedge in the ABD bucket. Gold is increasingly less a trade against one Fed meeting or one CPI print than a trade against the architecture of the decade itself.
ABD — The EM Extension
Hartnett’s Anything But the US Dollar framework naturally spills into emerging markets. A softer dollar loosens financial conditions across much of EM, improves the local-currency return profile for foreign investors and gives capital another reason to look beyond the US after years of American exceptionalism.
Politics now becomes part of the screen. Hartnett points to Latin America, where markets have rewarded the shift toward more business-friendly governments, and sees Brazil’s October 4 election as the next major directional test. The region has already produced a remarkable run of right-leaning electoral victories since early 2025; Brazil now decides whether that political momentum extends to its largest economy.
That makes Brazil more than an isolated election trade. A market-friendly outcome would reinforce the broader case for LatAm assets at exactly the moment ABD is already pushing investors toward non-dollar exposure. A reversal would test how much of that political premium is now embedded.
AI — Long the Bubble, Short the Financing
Hartnett’s final acronym is the most paradoxical: AI — All-In on AI.
His preferred expression, however, is short AI bonds.
The logic is straightforward. An AI buildout running above $1 trillion of capex, combined with increasingly negative net cash flow across parts of the ecosystem, means the financing requirement keeps rising. More investment therefore means more issuance, leaving the credit side of the AI boom carrying a very different risk profile from the equity side.
Hartnett first pushed this trade in late 2025, and in 2026 it has proved far more rewarding than simply chasing AI equities higher.
Yet he is not calling the top of the bubble. Quite the opposite. His preferred late-cycle strategy remains to own both hubris and humiliation at the same time: stay long the dominant speculative theme while also buying the neglected cyclical assets that tend to get dragged higher during the final nominal-growth surge.
History has produced versions of this before. EM caught the late-stage lift during the internet mania of 1999; oil exploded into the final stages of the subprime/China boom in 2007–08. Hartnett thinks the next beneficiaries could be the consumer and China, precisely because both remain far enough behind the current leadership to have room for a catch-up move.
The political constraint may ultimately matter more than valuation.
Texas is becoming an unusually clean laboratory. The state already hosts hundreds of data centres, with many more proposed, but the buildout is increasingly colliding with voter concerns over electricity costs, grid reliability and affordability. Governor Abbott’s temporary pause on further expansion is therefore not just an energy-policy story; Hartnett sees it as an early sign that political tolerance for unlimited AI infrastructure spending may be reaching its boundary.
That creates a fairly stark binary into November. If Republicans retain the Senate and Abbott holds Texas, Hartnett thinks the runway remains open for equities — particularly AI — to push into a genuinely bubbly 2027. If Democrats take the Senate and the Texas governor’s mansion on November 3, he sees scope for a much sharper reset: stocks down more than 10%, with the dollar and bond yields falling alongside them into year-end.
So the final constraint on the AI boom may not come from earnings, valuation or even the bond market. It may come from voters deciding that the infrastructure underneath the boom is becoming too expensive.
And with that, Hartnett turns from the structural playbook to the calendar — the sequence of market events over the next few months that could decide which of these trades breaks first
Aug 28th: Warsh speech at Jackson Hole
Sep 4th: Aug payrolls
Sep 11th: Aug CPI
Sep 16th: FOMC (hike probability currently 35%)
Sep 18th: BoJ (hike probability 74%)
Sep 24th: Trump-Xi summit
Oct 4th: Brazil election
Hey Mr. Innes, I have been enjoying your clear write up and the macro views. But, it would be nicer if you could sort of give us some ideas on where in particular a position can be established ( like is there an ETF for hong Kong real estate)...
Here’s hoping Gov Abbott loses and Republicans lose the Senate. We could all use lower interest rates and fewer data centers. Stocks down 10% is peanuts. A small correction.